
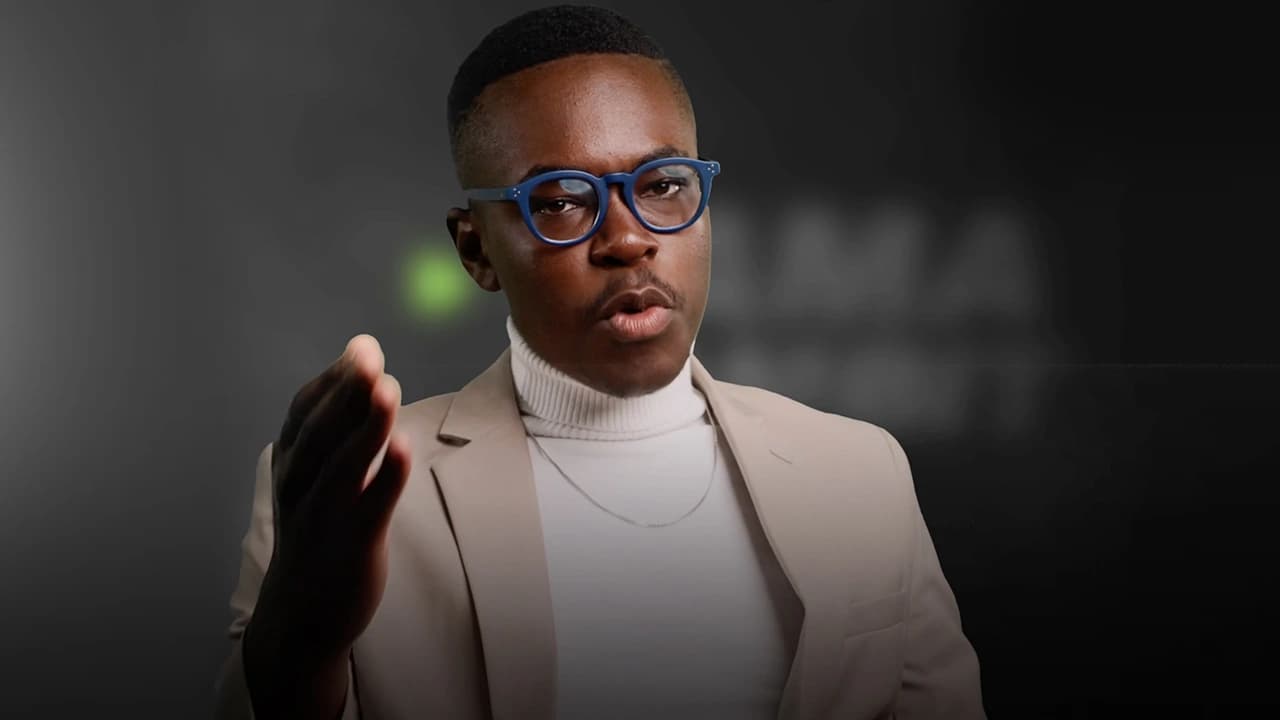
SA Reserve Bank Governor, Lesetja Kganyago, dashed the hopes of consumers who were expecting to save few hundred rands on their bond, vehicle and other credit instalments when he announced the decision to keep interest rates on hold on Thursday.
Kganyago announced that the bank’s Monetary Pricing Committee (MPC) had elected to retain the central bank’s repo rate at 7%, signalling a cautious approach to monetary policy amid complex economic conditions, with four Monetary Policy Committee (MPC) members voting to hold rates and two members advocating for a 25 basis point cut.

Bank’s strategic patience
Governor Lesetja Kganyago delivered a nuanced explanation of the decision, emphasising the bank’s strategic patience and the influence of spiralling administered prices which include Eskom’s electricity tariffs and municipal water tariffs as well as rising food prices on the bank’s decision.
“Overall, we expect headline inflation to average 3.4% this year and 3.6% next year, before reverting to 3% during 2027 and we assess the risks to the inflation outlook as balanced,” Kganyago said.
“Against this backdrop, the MPC decided to keep the policy rate unchanged at 7% – four members preferred to keep rate on hold, while two favoured a cut of 25 basis points. Since September last year we have reduced rate by 125 basis points, and we want to see how this is affecting the economy, how expectations evolve and how inflation risks are resolved … as inflation returns to the bottom end of the three to 6% target range. The MPC emphasises that stabilising inflation at 3% rather than 4.5% implies a lower, longer term level for the policy rate,” he said.
Global economic environment
He said the global economic environment provided a mixed but relatively supportive backdrop.
Kganyago highlighted that “market volatility has subsided” and policy rates have been cut in the United States and United Kingdom. Commodity prices have risen, with oil prices remaining contained, creating favourable conditions for emerging markets like South Africa.
Domestic economic indicators show promising signs. The SARB upgraded its growth forecast from 0.9% to 1.2%, driven by a surprisingly strong second-quarter GDP performance.
“Last week’s GDP release surprised on the upside, with the highest quarterly growth rate in two years,” Kganyago said.
However, he cautioned against over-optimism saying ‘we do not want to overstate the importance of one good quarter.”
Monetary policy committee
Inflation remains a critical focus for the monetary policy committee. The bank anticipates headline inflation will peak around 3.4% this year, with multiple factors contributing to price pressures. Administered prices, particularly electricity, play a significant role in this outlook. The bank now incorporates a nearly 8% electricity price inflation in its calculations, up from the previous 6% projection.
“Higher administered prices are not only a problem for inflation, but they actually also have an impact on growth,” Kganyago said. Th
“The solution to this crisis is not a higher level of inflation but rather sector specific reforms to improve efficiency … we have going to have to rein in administered prices, which entails a process of engagement with the administered price setters,” he said.
Food and fuel prices
Kganyoago said food and fuel prices continue to exert inflationary pressures. The bank observed that fuel prices are declining more slowly than previously expected, while food prices, particularly meat and vegetables, are contributing to upward price movements. Despite these challenges, core inflation remains contained at around 3%.
Kganyago explained that the effect of a single rate cut is estimated at 12 to 18 months, which underpins the committee’s measured approach to its interest rate decision.
Inflation expectations are showing encouraging signs. The latest survey indicates inflation expectations settling below the midpoint of the target range, which the bank views as a positive trend.
“They have declined for the first time to below the midpoint of the inflation target …we look forward to agreeing a new target as soon as is practical to better anchor inflation expectations,” he said, highlighting that the bank is having ongoing discussions with the National Treasury.
Roodt understands reasoning
Efficient Group economist Dawie Roodt said he had expected the bank to cut interest rates but he understood the committee’s reasoning for the decision.
“I was actually expecting them to cut rates for a couple of reasons. One is that inflation came in lower than expected. Another one is inflation expectations are coming in lower. And of course, the Americans are cutting rates as well,” Roodt said.
“I still believe there’s a there’s a gap for rate cuts, so I think next time around, they will cut rates,” he said.
However, Roodt said he was not “too critical” of Kganyago as it is “very clear he is absolutely determined to get inflation down to 3% so well done for him”.
“I am neither hot nor cold about today’s decision”, he said.
Roodt said the absence of a rate cut this time around would not really make too much of a difference to food prices and the cost of living for consumers over the next few months.
“If there was a cut it would have been 25 basis points which is not going to move the needle. So it’s either here nor there. Everything eventually adds up. But in two months’ time, I’m pretty sure we’re going to see a rate cut,” Roodt said.


